
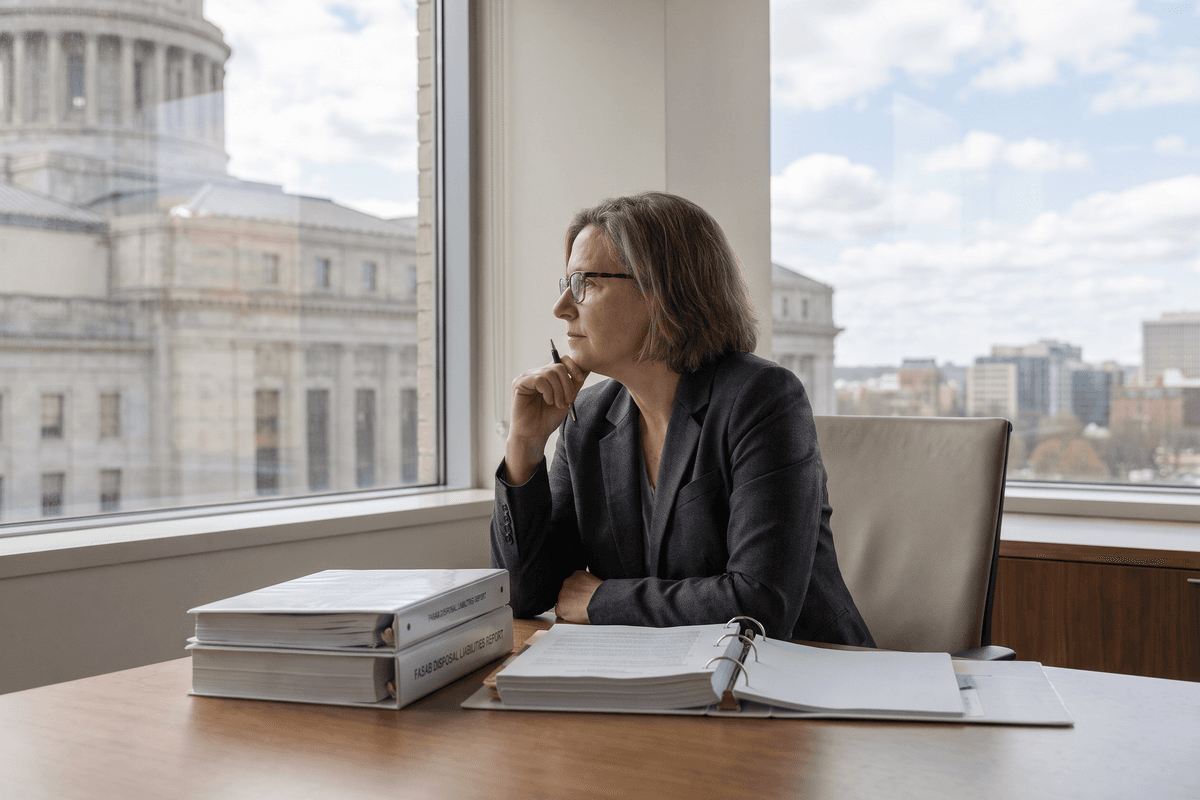
Most accounting professionals think of standard setting as a private-sector story, with new rules arriving in FASB and PCAOB press releases and reshaping audit files every few quarters. But the Federal Accounting Standards Advisory Board is quietly doing the same kind of work for the federal government, and its latest move deserves attention. In its fiscal 2026 annual report and three-year work plan, FASAB opened a public feedback period on accounting guidance for environmental and disposal liabilities. For CPAs who serve federal agencies, contractors, or any client carrying legacy cleanup obligations, that request is a signal worth reading closely.
Why a Standard Setter's Work Plan Matters to Practitioners
A work plan is easy to skim past. It is a list of projects, timelines, and priorities. Yet for practitioners, it functions as an early warning system. Projects that appear on a board's agenda today tend to become exposure drafts, then final standards, then audit and reporting requirements that land on engagement teams. Reading the work plan tells you where the next set of questions will come from.
FASAB sets generally accepted accounting principles for federal entities, so its decisions shape how agencies, government corporations, and some related entities report their financial position. Its guidance also flows into the audit work performed by inspectors general and independent auditors, and into the financial statements that Congress and the public rely on. When FASAB reopens guidance on a topic, the ripple effects can be broad.
Inside the Disposal Liabilities Question
The core issue is how the federal government should recognize and measure obligations tied to cleaning up and disposing of assets. Those obligations can include environmental remediation at legacy sites, decommissioning of equipment, and the handling of property containing hazardous materials. They share a defining feature: the cash outflow may arrive years or decades after the activity that created the obligation, and the estimate depends heavily on assumptions about technology, timing, and regulation.
Private-sector practitioners will recognize the pattern. Under U.S. GAAP, asset retirement obligations under ASC 410-20 require entities to recognize the fair value of legally required retirement costs and update those estimates over time. Federal reporting faces similar judgment calls, but with additional complexity: the government's assets and obligations span agencies, appropriation structures, and congressional funding decisions. Feedback on FASAB's proposed guidance will help determine whether the board tightens, clarifies, or modernizes how these liabilities are presented.
How This Fits a Broader Pattern of Standard-Setting Activity
FASAB's announcement does not stand alone. The same news cycle surfaced a set of developments across the profession's rule-making bodies, each with practical implications. Taken together, they suggest a common theme: regulators and standard setters are pushing for clearer documentation, sharper disclosure, and more explicit professional judgment.
| Development | Issuer | Practical Implication for U.S. CPAs |
|---|---|---|
| Proposed SOC 2 description criteria updates | AICPA | Service organization reports may require tighter, more consistent system descriptions |
| Comfort-letter amendments to AS 6101 and five new enforcement units | PCAOB | Comfort letter practice may need refreshed procedures, and enforcement scrutiny is becoming more specialized |
| Ethics exposure draft for alternative practice structures | AICPA PEEC | Firms with private-equity or alternative ownership should track independence and structure requirements |
| Executive compensation disclosure overhaul (Reg. S-K Item 402) | SEC | Disclosure teams may see a materiality-driven approach replacing some boilerplate |
The table is not exhaustive, but it illustrates the breadth of the moment. A practitioner advising a public company may face SEC disclosure changes and PCAOB enforcement shifts in the same quarter. A firm with a government practice may face FASAB's liability questions alongside audit documentation expectations. The common thread is that judgment and documentation are becoming the differentiators.
The Human and Technology Dimension
Several of the related developments touch on how firms use technology. A Wolters Kluwer 2026 Future Ready Accountant report found that 36% of accounting firms have a written AI policy, with growing emphasis on workflow integration and professional review of AI work. That figure matters because long-horizon estimates like disposal liabilities are exactly the kind of work where automated models can accelerate calculations but cannot own the assumptions behind them.
Meanwhile, the AICPA and CIMA's Rise2040 initiative has been gathering insights from thousands of finance professionals on AI, trust, and human judgment. Those findings align with what standard setters are signaling: the profession's value increasingly lies in interpreting uncertainty, not in producing numbers faster.
"The board is seeking feedback on its work plan and on accounting guidance for environmental and disposal liabilities."
— FASAB public feedback announcement
Practical Steps for U.S. Accounting Professionals
Whether or not you audit federal entities, the FASAB moment offers a useful checklist for staying ahead of standard-setting cycles:
- Read work plans, not just final standards. Projects on a board's agenda today shape the questions clients ask next year.
- Map long-tail obligations in your client base. Identify retirement, remediation, and decommissioning liabilities, and check whether estimates are updated on a consistent schedule.
- Document assumptions explicitly. Discount rates, timing, and regulatory expectations for disposal costs should be traceable and reviewable.
- Engage in comment processes. Feedback periods are where practitioners can flag implementation problems before rules become effective.
- Build cross-standard fluency. A team that understands federal, private-sector, and PCAOB requirements is better positioned for clients who operate across all three.
What to Watch Next
FASAB's feedback request is an early step, not a final answer. The months ahead will reveal how the board weighs comments on recognition thresholds, measurement methods, and disclosure depth for disposal liabilities. Practitioners should watch for exposure draft language that clarifies who bears responsibility for estimates when cleanup obligations span multiple agencies, and whether the board signals a timeline for final guidance.
The larger lesson is that the accounting profession's rule-making ecosystem is more interconnected than it appears. Federal standard setters, the PCAOB, the AICPA, and the SEC are each refining the same core idea: that credible financial information depends on transparent judgment, documented assumptions, and professionals willing to stand behind them. The firms that treat this moment as a reading assignment, rather than a background notice, will be the ones prepared when the next exposure draft lands on their desks.