
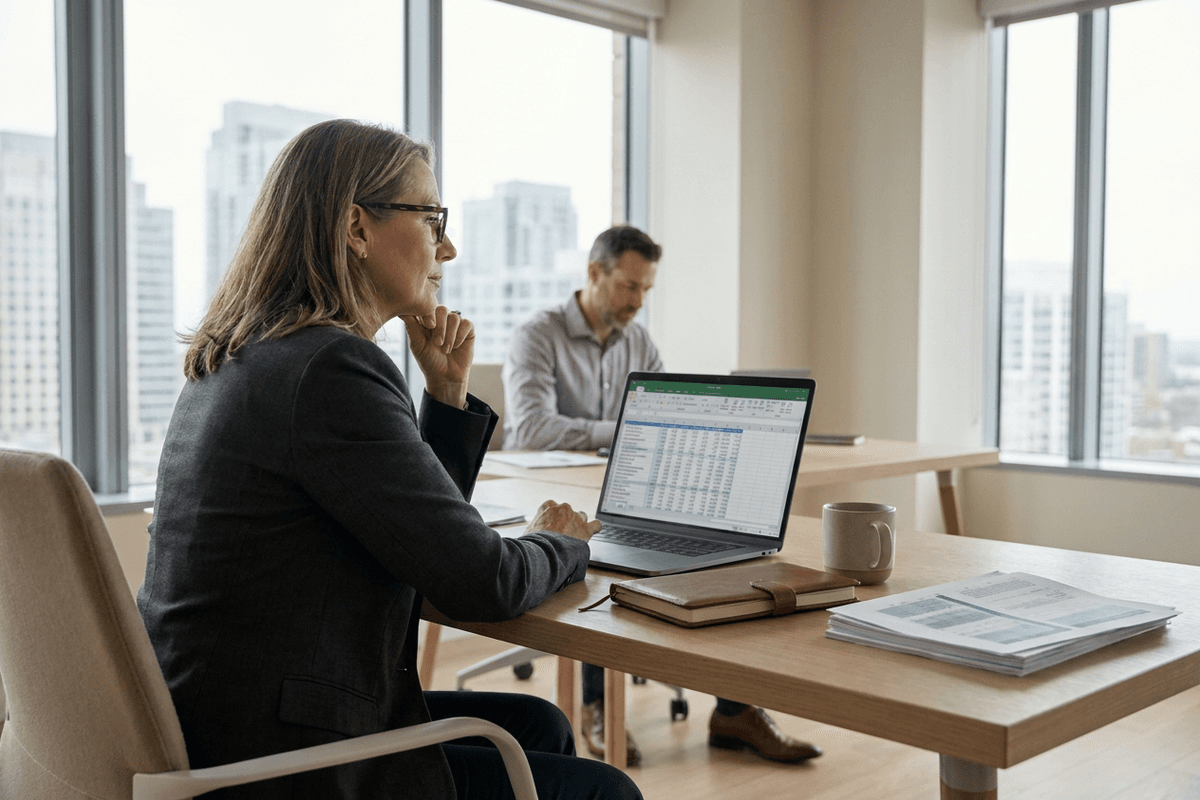
Across the United States accounting landscape, practice leaders are finding that incremental operational tweaks are no longer sufficient to navigate the compounding pressures of technical rule changes, workflow automation, and human capital friction. Between the rapid deployment of agentic artificial intelligence in compliance pipelines, newly released multi-year tax planning baselines, and intensifying debates over workplace presence, firm managing partners are steering through one of the most operationally demanding quarters in recent memory.
According to recent industry analysis highlighted in an AICPA and CPA.com technology roundtable roundup, the profession has moved decisively past the theoretical stage of generative tools. Instead, firms are directly embedding purpose-built AI automation tools into tax preparation and document-intake workflows to mitigate persistent capacity bottlenecks. Yet as software rewires the back office, leaders must simultaneously calibrate their multi-year advisory projections against the Internal Revenue Service’s latest statutory updates and manage a workforce caught between executive in-office mandates and hybrid flexibility.
The Algorithmic Workflow: Insights from AICPA and CPA.com
The transition from generic large language models (LLMs) to domain-specific, contextual tax workflows represents the single most consequential shift in firm technology. Discussions emerging from AICPA and CPA.com industry forums emphasize that while early AI experiments focused primarily on draft correspondence and surface-level research, today’s top-performing platforms are directly integrating with tax engines, trial balance software, and unstructured client workpapers.
Automated document extraction—long a source of friction due to inconsistent scans, handwritten schedules, and varied brokerage formats—has reached an inflection point. Contemporary systems are now executing multi-layered reconciliation: reading Schedule K-1s, validating footings against partnership agreements, and flagging passive activity discrepancies before a junior associate ever touches the file.
"The objective of embedding AI into the tax workflow is not to eliminate professional scrutiny, but to move human review to the point of highest value. When the software handles the ingestion, reconciliation, and mechanical cross-checking, the CPA’s role elevates immediately to strategic advisory and exception handling."
However, technology leaders at the AICPA and CPA.com roundtable stressed that adopting these automation layers demands rigorous internal controls. Firms must maintain verifiable audit trails showing how an automated system parsed source data, which prompts or heuristics were deployed, and where an authorized human professional signed off on statutory interpretations.
Calibrating Long-Term Projections: IRS 2027 Inflation Adjustments
While firms re-engineer workflow mechanics, tax advisory practices must incorporate newly finalized technical baselines into their forward-looking wealth planning and corporate advisory models. The Internal Revenue Service has published its annual cost-of-living adjustments, providing clarity for multi-year estate, gift, and income planning through the IRS annual inflation adjustments for tax year 2027.
These adjustments carry profound implications for advisory engagements, particularly for high-net-worth clients and closely held business owners who are modeling liquidity events, estate transfers, and capital expenditure timing:
- Tax Bracket Creep Mitigation: Adjusted marginal tax rate thresholds provide updated boundaries for strategic income acceleration or deferral, especially for pass-through entity owners balancing Sec. 199A calculations against individual rate jumps.
- Standard Deduction Expansion: Incremental upward adjustments continue to alter the threshold calculation for itemized deductions, requiring practitioners to revisit bunching strategies for charitable contributions and state tax payments.
- Transfer Tax Thresholds: Updated unified credit equivalents for estate and gift taxes demand immediate review in trust and estate planning engagements, especially as practitioners structure multi-generational wealth preservation strategies ahead of potential legislative sunsets.
| Operational Dimension | Legacy Firm Approach | Modernized Strategic Practice |
|---|---|---|
| Tax Prep & Document Intake | Manual scan-and-populate; junior staff keying K-1s and 1099s | Agentic AI document parsing with automated cross-referencing and anomaly detection |
| Multi-Year Advisory | Reactive year-end reviews using trailing historical data | Dynamic forecasting incorporating IRS inflation parameters and statutory trigger models |
| Workplace Policy | Top-down rigid mandates or unmonitored ad-hoc remote work | Structured hybrid expectations anchored in apprenticeship, transparency, and output |
| Technical Standard Scoping | Over-engineered disclosure reviews for simple non-standard instruments | Streamlined equity/liability evaluations aligned with emerging FASB and AICPA frameworks |
The Personnel Dilemma: Workplace Mandates vs. Professional Retention
Even the most sophisticated software stack and technical mastery cannot compensate for fractured human capital. The ongoing tug-of-war over return-to-office (RTO) policies has reignited tension across the profession, underscored by leadership stances and restructuring developments highlighted in recent industry news coverage regarding executive workplace policies at major firms.
While top executives at national accounting powerhouses continue to argue that physical presence is indispensable for on-the-job training, firm culture, and audit skepticism, mid-tier and regional firms are leveraging flexibility as an aggressive recruiting wedge. The friction is particularly acute among senior associates and managers—the exact cohort bearing the heaviest brunt of compliance volume.
The Practical Trade-offs for Firm Leadership
- The Apprenticeship Deficit: First- and second-year associates undeniably benefit from shoulder-to-shoulder learning and passive observation. However, rigid full-time mandates without intentional in-office mentorship create resentment rather than professional growth.
- Talent Arbitrage: Regional firms that offer structured, predictable hybrid schedules are actively drawing experienced talent away from national networks that enforce inflexible physical attendance policies.
- Measuring Output Over Presence: With AI tools accelerating compliance turnaround, evaluating staff on desk-time rather than realized client value and data governance creates perverse operational incentives.
Technical Convergence: Easing Financial Reporting Friction
Complementing these workflow and staffing challenges is a parallel effort by standard-setters to remove unnecessary complexity from corporate reporting. For instance, the Financial Accounting Standards Board has introduced targeted relief through its exposure draft simplifying equity-linked contracts. By streamlining the evaluation under ASC 815-40 for whether instruments like warrants qualify for equity classification, FASB is helping firms reduce the disproportionate audit hours previously spent on non-cash, highly technical contract parsing.
Concurrently, as private equity continues to reshape firm capitalization, the AICPA Professional Ethics Executive Committee’s focus on proposed ethics guidance for alternative practice structures establishes necessary guardrails to protect attest independence while enabling capital investment into cutting-edge tax tech.
The Strategic Path Forward for Practice Leaders
As firms prepare their operating budgets and staffing allocations for the upcoming cycles, surviving the current transformation requires a disciplined, three-pronged strategy:
1. Institutionalize AI Quality Control: Avoid decentralized, rogue AI usage by establishing firmwide protocols. Test and deploy verified tax-workflow tools that feature explicit source attribution, robust SOC 2 compliance, and direct API integration into engagement platforms.
2. Translate Thresholds into Advisory Revenue: Leverage the IRS’s updated 2027 parameters to proactively initiate client check-ins. Turn mechanical compliance updates into high-margin advisory discussions on estate planning, entity choice, and strategic distribution planning.
3. Adopt Purpose-Driven Workplace Policies: Move past binary "in-office versus fully remote" dogmatism. Design in-office requirements around specific collaborative activities—complex technical reviews, team training, and client presentations—while honoring flexibility for heads-down technical execution.
The accounting profession is entering a phase where technological leverage and human culture must operate in tandem. Firms that embrace algorithmic efficiency while fostering a culture of mentorship and clear-eyed technical advisory will not only weather current market strains—they will define the operating standards of the modern CPA firm.